
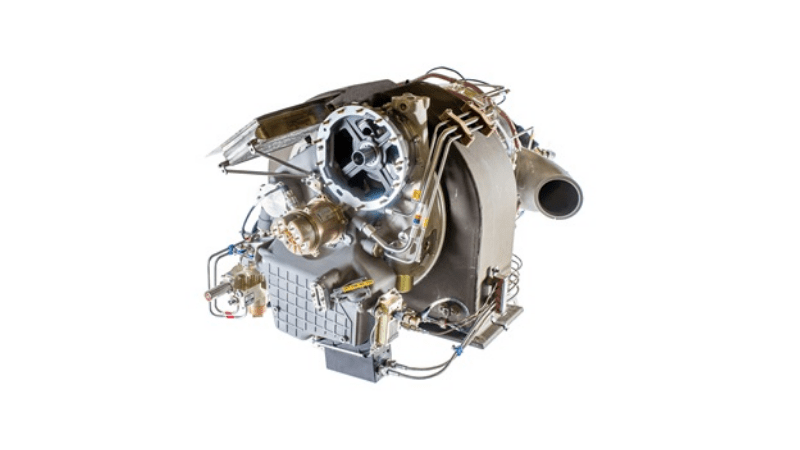
Not all Boeing APU models face the same supply conditions in 2026. The availability of serviceable units, the depth of the lessor market, and the lead times operators should expect vary significantly depending on which platform is being supported. The Boeing 737 NG operates in a different supply environment than the 767, the 777, or the 747, and treating them as comparable sourcing markets produces planning errors that show up as AOG delays and cost premiums. Fleet teams that understand how supply conditions differ across platforms can set appropriate planning thresholds, establish the right lessor relationships in advance, and avoid the reactive sourcing scenarios that consistently produce the worst outcomes. Operators who plan sourcing based on narrowbody benchmarks and then apply those expectations to widebody models consistently encounter delays and cost premiums that planning would have avoided.
This article covers each major Boeing auxiliary power unit platform and what operators should expect from the market in 2026.
Narrowbody Supply: Broad but Not Unlimited
The 737 NG fleet is one of the largest active commercial fleets in the world, and the GTCP131 series APUs that serve it benefit from a correspondingly broad supply pool. Serviceable GTCP131-9A and GTCP131-9B units are available across multiple lessors and distributors, and lead times for planned sourcing events are generally manageable. The depth of the market means operators have options when sourcing and can negotiate on documentation standards, limiter values, and delivery terms.
That said, depth does not mean unlimited availability. During periods of peak fleet utilization, particularly following demand surges that drive higher cycle accumulation across the global 737 fleet, supply tightens and lead times extend. Operators who rely on the assumption that a unit will always be available quickly because the market has historically been accessible take unnecessary risks. The Boeing APU sourcing market for the 737 NG rewards planning, even when reactive sourcing is technically possible.
767 Supply: Contracting with Active Freighter Demand
The Boeing 767 fleet presents a more nuanced supply picture. Passenger 767 operators have been retiring aircraft for several years, reducing the overall fleet size. However, 767 freighters remain in active service with major cargo carriers, sustaining demand for GTCP331-200ER units in a market where supply is contracting alongside passenger fleet retirements.
The result is a tighter supply pool than the narrowbody market, but with concentrated demand among a smaller number of freighter operators. Lead times for GTCP331-200ER sourcing are longer than for GTCP131 series models, and the range of available lessors is narrower. Operators managing 767 freighter fleets should begin sourcing further in advance of planned removals than they would for narrowbody events and should establish relationships with lessors who carry direct 767 APU inventory before a removal occurs.
777 Supply: High Demand, Specialized Inventory
The Boeing 777 remains one of the most widely operated widebody aircraft in commercial service, and demand for GTCP331-350C units reflects that. The supply pool for this model is more specialized than the narrowbody market, with fewer lessors carrying direct inventory and longer lead times for sourcing events that are not planned well in advance.
The 777’s role as a primary long-haul and freighter platform means AOG events on this aircraft carry a high revenue impact per day. Operators who manage 777 fleets without pre-established APU sourcing relationships face the worst combination of outcomes when an unscheduled removal occurs: high daily revenue exposure, a specialized supply pool, and no pre-negotiated access to inventory.
747 Supply: The Tightest Market
The Boeing auxiliary power unit supply conditions for the 747 family are the most constrained of any Boeing platform in 2026. The PW901A for the 747-400 and the GTCP331-500B for the same aircraft are both served by a contracting fleet. As passenger 747-400 operators continue retiring aircraft, the pool of available serviceable units shrinks. Freighter operators who depend on the 747-400 for high-volume cargo operations face a sourcing market that becomes more time-sensitive with each passing year.
Operators managing 747 fleets should treat APU sourcing as a strategic planning function, not a transactional one. Establishing relationships with lessors who hold direct 747 APU inventory, setting planning thresholds that trigger sourcing well ahead of minimum acceptance values, and maintaining current LLP limiter data per unit are the practical steps that separate operators who manage this market well from those who encounter it under pressure.